 780-466-9898
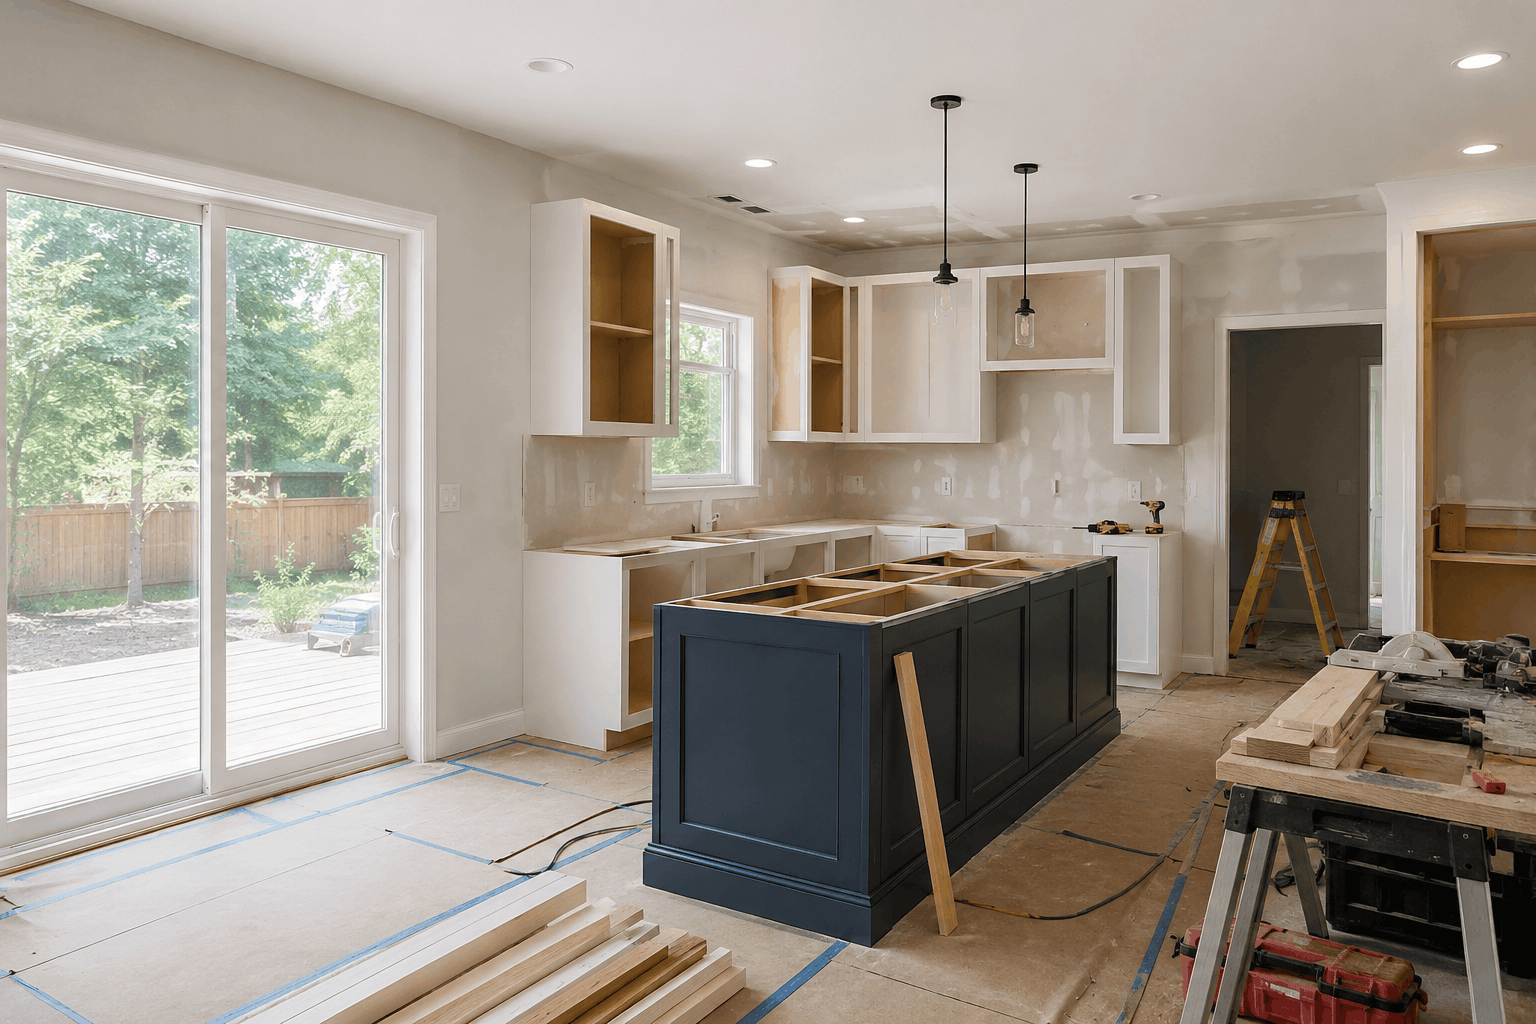
Planning a kitchen upgrade, finishing your basement, or making important repairs to your home? If you own a property in Edmonton, refinancing your mortgage may be one way to access funds for renovations without relying entirely on personal loans or credit cards.
A mortgage refinance allows eligible homeowners to replace their existing mortgage with a new mortgage, potentially borrowing more than they currently owe. The additional funds may be used to finance home improvements, depending on your available home equity, income, credit profile, and lender requirements.
Before deciding whether to refinance your mortgage for renovations in Edmonton, it is important to understand how the process works, what it costs, and whether the long-term financial impact makes sense for your situation.
Yes. Eligible homeowners in Edmonton may be able to refinance their mortgage to access equity in their property and use the funds to pay for renovations.
Home equity is the difference between your home’s current market value and the outstanding balance of your mortgage and other debts secured against the property.
For example, if your home is worth $500,000 and you owe $300,000 on your mortgage, you have approximately $200,000 in equity before accounting for any other secured debts and transaction costs.
However, having $200,000 in equity does not automatically mean you can borrow that entire amount. The lender will assess your financial circumstances, the property’s value, applicable lending limits, and your ability to make the new mortgage payments.
For many homeowners, refinancing may be worth exploring when the planned renovations require a substantial budget and the homeowner wants to spread repayment over a longer period.
When you refinance your mortgage, your existing mortgage is replaced with a new mortgage under updated terms. If the new mortgage is larger than your existing balance and any applicable amounts paid out at closing, the remaining funds may be available for your renovation project.
Here is how the process generally works.
Start by identifying the improvements you want to make and estimating their total cost.
Your renovation budget should account for:
Materials and contractor labour
Permits and inspection fees, where required
Electrical, plumbing, or structural work
Temporary accommodation, if necessary
A contingency fund for unexpected expenses
Obtaining written estimates from qualified contractors can help you determine how much financing you actually need.
Review your current mortgage balance and estimate your home’s current market value.
A lender may require an appraisal or another form of property valuation before approving a refinance. Your available equity will help determine how much additional financing may be possible.
Your mortgage broker or lender will review your existing mortgage, income, employment, credit history, other debts, and overall ability to manage the proposed payments.
You should also review your existing mortgage contract to determine whether breaking it early could trigger a prepayment penalty or other fees.
Compare the proposed mortgage’s interest rate, amortization period, payment amount, fees, and flexibility with your existing mortgage.
A lower monthly payment is not necessarily the cheapest option over the life of the loan. Extending the amortization period or borrowing more money can increase the total interest you pay.
If you meet the lender’s requirements and accept the terms, the lender will arrange the necessary documentation and closing process.
Once the refinance is completed and funds are released, you can use the available proceeds for your renovation expenses in accordance with the loan terms.
The amount you may be able to borrow depends on your home’s appraised value, existing mortgage balance, other secured debts, lender policies, and your ability to qualify.
For many conventional mortgage refinances in Canada, the total borrowing secured against the home is generally limited to 80% of the property’s appraised value, subject to applicable rules and lender approval.
Consider the following hypothetical Edmonton homeowner:
| Item | Amount |
|---|---|
| Estimated home value | $500,000 |
| Current mortgage balance | $300,000 |
| Illustrative 80% lending limit | $400,000 |
| Potential additional borrowing before costs | $100,000 |
| Planned renovation budget | $60,000 |
In this example, the difference between the illustrative lending limit and the current mortgage balance is $100,000.
The homeowner might be able to refinance to access enough money for the $60,000 renovation. However, the actual approved amount may be lower after considering the lender’s assessment, other secured debts, fees, and qualification requirements.
Important: This is an illustration, not a borrowing guarantee or a personalized mortgage quote. Your approved financing will depend on the lender’s criteria and your financial circumstances.
Depending on your lender’s requirements and your approved financing, you may be able to use refinance proceeds for a wide range of home improvements.
Kitchen and bathroom upgrades can improve everyday functionality and modernize an older property. Projects may include replacing cabinets, installing new countertops, upgrading fixtures, or improving layouts.
Finishing an unfinished basement can create additional living space for a family room, home office, recreation area, or other permitted use. Make sure your budget includes any required permits, safety improvements, and professional work.
Replacing an aging roof, improving windows, or addressing exterior damage may help maintain your property’s condition and improve energy efficiency.
Some homeowners need financing for foundation work, plumbing upgrades, electrical improvements, or other significant repairs. These projects may require professional inspections, permits, and detailed cost estimates.
You may also wish to finance accessibility upgrades, insulation, or other improvements that make your home more comfortable and practical.
Keep in mind that renovation spending does not guarantee an equivalent increase in property value. The financial return depends on the quality of the work, local market conditions, buyer preferences, and the type of improvement.
Mortgage refinancing can provide several advantages for homeowners who qualify.
Access to existing home equity: Rather than selling your property to access its equity, you may be able to borrow against some of the value you have built up.
Potentially lower borrowing costs: Mortgage financing may carry a lower interest rate than some unsecured borrowing options. However, the actual rate and total cost depend on your circumstances, mortgage terms, and lender.
One consolidated mortgage payment: If you replace your existing mortgage with a new mortgage, you generally have one new scheduled mortgage payment rather than a separate payment for the renovation borrowing.
Funding for larger projects: A refinance may provide access to more money than some personal credit products, provided you meet the lender’s requirements.
Opportunity to review your mortgage terms: Refinancing gives you an opportunity to review your interest rate, payment structure, and amortization period alongside your renovation financing needs.
These advantages should be weighed against the cost of refinancing, potential penalties, and the risk of increasing the debt secured against your home.
Refinancing is not automatically the best choice for every homeowner. Consider the following potential drawbacks before proceeding.
If you refinance before your current mortgage term ends, your lender may charge a prepayment penalty. The amount can vary depending on your mortgage type, contract, and lender’s calculation.
Borrowing additional money can increase your required mortgage payments. Your payments may also change because of a different interest rate or amortization period.
If you spread renovation costs over many years, you could pay significantly more interest than you would with a shorter-term borrowing option.
Depending on your existing mortgage and the new financing arrangement, costs may include appraisal fees, legal fees, discharge fees, and other lender or transaction charges.
Unlike unsecured borrowing, a mortgage is secured against your property. Missing payments can put your home at risk.
Before refinancing, make sure the proposed payment is affordable even if your household expenses increase or your income changes.
Homeowners in Edmonton may have several financing options. The right choice depends on the project budget, available equity, repayment preferences, and overall financial situation.
| Financing option | How it works | What to consider |
|---|---|---|
| Mortgage refinance | Replaces your existing mortgage with a new mortgage, potentially with additional borrowing | Prepayment penalties, closing costs, new mortgage terms, and long-term interest |
| Home equity line of credit (HELOC) | Provides access to a revolving credit limit secured against your home | Variable interest may apply, payments can fluctuate, and borrowing is subject to qualification |
| Personal loan | Provides a fixed amount of unsecured or secured borrowing, depending on the product | Interest rates, fees, loan term, and monthly payment |
| Savings | Uses money you have already set aside | Avoids new borrowing costs but reduces available cash reserves |
A mortgage refinance may suit a homeowner planning a major renovation who wants to restructure an existing mortgage. A HELOC may offer more flexible access to funds over time, while a personal loan may be worth considering for a smaller project.
A mortgage professional can help compare the actual costs of these options rather than relying on interest rates alone.
You do not necessarily need to wait until your mortgage renewal date to refinance. However, refinancing during an existing term may involve additional costs.
Before making a decision, ask your current lender for a mortgage payout statement and determine whether a prepayment penalty applies. Compare those costs with the potential benefits of accessing renovation funds now.
You should also consider whether your mortgage has portability or other features that may affect your options.
If your renewal date is approaching, compare the available refinancing and renewal options before committing to new terms. The best timing will depend on your renovation schedule, current contract, financial position, and lender offers.
Preparing your documents before applying can help make the process more efficient.
Use this checklist to get started:
Lenders may request additional documents depending on whether you are employed, self-employed, refinancing an investment property, or applying under a specialized lending program.
Yes, if you qualify for refinancing and your lender approves the additional borrowing. The available amount will depend on your home equity, income, debts, property valuation, and applicable lending limits.
For many conventional mortgage refinances, lenders generally limit total borrowing secured against the property to 80% of its appraised value. Your specific requirements may vary by lender and financing structure. Having sufficient equity does not guarantee approval.
It depends on the interest rate, fees, repayment period, and whether you incur a penalty for breaking your existing mortgage. A refinance may offer a lower rate, but spreading repayment over a longer period can increase total interest costs.
Possibly. The lender will consider your home’s value, remaining mortgage balance, other secured debts, income, credit profile, and ability to qualify. A large outstanding balance may limit the additional funds available.
Some renovations may improve marketability or property value, but the result is not guaranteed. The impact depends on the type and quality of work, the property’s location, buyer demand, and current market conditions.
Yes, subject to your lender’s requirements and your ability to qualify. However, breaking a fixed-rate mortgage early can result in a significant prepayment penalty. Request a payout statement and compare the full costs before proceeding.
Compare the amount you need, your available equity, refinancing fees, current mortgage terms, new payment, and total interest cost. Consider alternatives such as a HELOC or personal loan, and assess whether the renovation justifies taking on additional debt secured against your home.
If you are planning a home renovation, understanding your financing options before starting construction can help you make a more informed decision.
Mortgage refinancing may allow eligible Edmonton homeowners to access some of their home equity to fund improvements, but the right approach depends on the property’s value, mortgage terms, borrowing costs, and financial goals.
The Mortgage Force Team at Mortgage Apply Online can help you explore mortgage options, understand the application process, and compare potential financing approaches for your situation.
Planning a renovation? Contact Mortgage Apply Online to discuss your mortgage refinancing options in Edmonton and determine which financing approach may suit your needs.
Disclaimer: This article is for general informational purposes only and is not financial, legal, tax, or mortgage approval advice. Mortgage availability, rates, lending limits, fees, and qualification criteria vary. Speak with a qualified mortgage professional and review your lender’s terms before making a borrowing decision.
Posted by MortgageApplyOnline On October 19th, 2026